Instant PayID withdrawals in Australia: timing
 Available in AU
PayID transfers can be real time after release, while operator checks, payment limits and bonus terms can affect the withdrawal process.
How PayID Payout Speed Works After Approval
PayID is an Australian bank-to-bank payment service that operates through the New Payments Platform (NPP). Payments sent through the Osko network can move between participating bank accounts in real time. That describes the transfer rail—not the time it takes an operator to approve a withdrawal request.
This distinction matters when you see the phrase “instant withdrawal”. It can refer to the payment phase after a request has been approved and released, rather than the complete journey from clicking “withdraw” to seeing cleared funds. The operator’s handling of the request and the bank-to-bank transfer are separate stages, with different processes and timing.
There is an important legal context for Australian readers. Under the Interactive Gambling Act 2001, providing real-money online casino games, including slots, poker and table games, to people in Australia is illegal for operators.
Two stages, two different clocks
A withdrawal can be thought of as having two broad stages. First, the operator receives and considers the request. Only after it approves and releases the payment can the transfer stage begin. PayID’s real-time capability applies to that later movement of funds, not automatically to the earlier decision.
If you’re looking for real-money PayID withdrawals in Australia, check the stated payout method and timing before choosing a casino. The details below show what is available about each operator, without assuming that PayID withdrawals are offered where they are not specified.
License: Curacao You can note that Golden Pokies is listed with a Curaçao licence. No PayID withdrawal details are provided.
License: Curacao Gaming Control Board OGL/2023/176/0095 (Hollycorn N.V.) GoldenCrown is listed with a Curaçao Gaming Control Board licence, OGL/2023/176/0095, held by Hollycorn N.V. You’ll need to check separately for PayID withdrawal information.
License: Curacao · Min. deposit: A$20 (POLi) Lucky Dreams lists a A$20 minimum deposit via POLi. That is a deposit detail, not confirmation of PayID withdrawals.
License: Curacao eGaming OGL/2023/174/0082 (Dama N.V.) · Min. deposit: A$15 LevelUp Casino lists a A$15 minimum deposit and a Curaçao eGaming licence, OGL/2023/174/0082, held by Dama N.V. PayID withdrawal details are not provided.
License: international iGaming licence – jurisdiction not named in the source · Payout speed: PayID 1-24 hours · Min. deposit: A$30 (PayID from A$10) House of Pokies lists PayID payouts within 1–24 hours and a A$30 minimum deposit, with PayID deposits from A$10. Its source describes the licence as international iGaming but does not name the jurisdiction.
License: Curacao eGaming (Roby Games Ltd) Roby Casino is listed with a Curaçao eGaming licence held by Roby Games Ltd. No PayID withdrawal timing or availability is specified.
License: Curacao (operating since 2017) · Min. deposit: A$20 Uptown Pokies is listed as operating since 2017, with a Curaçao licence and a A$20 minimum deposit. The available details do not specify PayID withdrawals.
License: Curacao, operated by Dama N.V. 7Bit Casino is listed with a Curaçao licence and is operated by Dama N.V. You’ll need to verify its PayID withdrawal options separately.
License: Curacao · Payout speed: crypto 30-60 minutes, fiat 1-5 days · Min. deposit: A$10 Wild Tokyo lists crypto payouts at 30–60 minutes and fiat payouts at 1–5 days, with a A$10 minimum deposit. These details do not specify a PayID payout timeframe.
License: Tobique Gaming Commission · Payout speed: crypto ~10-15 minutes, fiat 1-5 days · Min. deposit: A$30 SkyCrown lists crypto payouts at approximately 10–15 minutes and fiat payouts at 1–5 days, with a A$30 minimum deposit. Its listed licence is from the Tobique Gaming Commission; PayID withdrawal details are not provided.
If the request is still awaiting approval, the fact that PayID uses a real-time payment network does not make the funds arrive. The request has not yet reached the point at which the payment rail can carry it. Once released, the transfer may move in real time through Osko, but that does not mean every request is approved immediately or every complete withdrawal is instant.
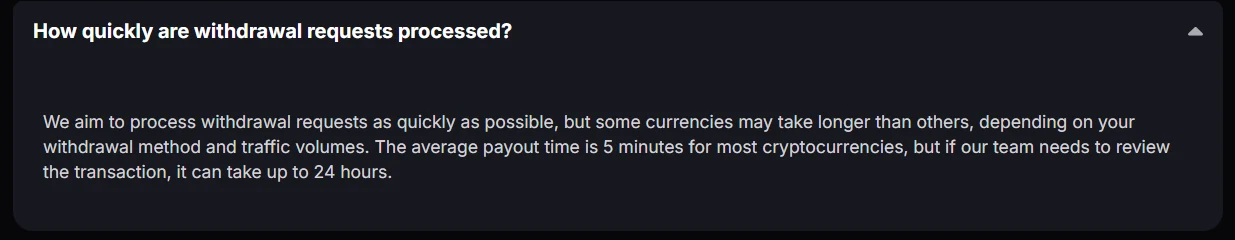
A specialist review has described funds as moving instantly once a PayID withdrawal is released by the operator. Read that as a description of the transfer phase, not a promise about the full process. A separate specialist review reported that some services advertised “instant” withdrawals while internal review meant the process could take as long as 24 hours. That account illustrates why the label alone cannot establish when a request will be approved or when money will reach an account.
What PayID does—and does not—control
PayID provides a way to identify a bank account for a transfer without relying on the recipient’s account number in the same manner as a conventional bank transfer. The underlying payment function is supported by the NPP, while Osko is the network through which the real-time transfer is processed. These terms describe connected parts of the payment process; they do not describe an operator’s approval system.
In practical terms, the operator must first decide that a withdrawal can be sent. The payment rail then carries the released funds towards the linked bank account. If the request has not been released, there is no outgoing PayID transfer for the network to process. If it has been released, PayID’s real-time design is relevant—but the wording should still be understood as describing the transfer mechanism rather than guaranteeing a particular end-to-end experience.
This is why “instant” needs a clear reference point. It may describe how quickly money moves after release, while the time before release belongs to the operator’s own process. A statement that does not distinguish those stages can leave you with the impression that a withdrawal request and its receipt are one continuous, immediate event. They are not the same thing.
Reading timing claims carefully
When assessing a timing statement, look for what event starts the clock. Does it mean the request has been submitted, approved, or actually released? Those moments are different. A claim about payment after release says little about how long the earlier review may take.
Also note whether a stated time is presented as a guaranteed service condition or as an observation reported by a review. A specialist review’s account of instant transfers describes what that source reported; it should not be treated as a universal commitment. The same caution applies to reports of a longer wait caused by internal review. These accounts show that an “instant” label may not cover every stage, but they do not establish a fixed time for every operator or request.
Attention: An “instant” label may describe the transfer phase after approval, but it does not guarantee that the entire process from request to receipt is immediate.
The most useful wording is precise about the boundary: the payment may be processed in real time after approval and release. That is materially different from saying that every withdrawal request will be processed immediately from the moment you submit it. PayID can make the transfer stage fast without controlling the operator’s queue, decision or release timing.
Why the distinction matters
If you are trying to understand a pending withdrawal, identify whether it is still being handled by the operator or whether it has already been released for payment. The payment method cannot explain a request that has not reached the transfer stage. Conversely, once a payment is released, the operator’s approval period is no longer the same question as the speed of the bank-to-bank movement.
Keep the words “approved” and “sent” separate, too. Approval indicates that the operator has agreed to proceed; release indicates that the payment has been initiated. A description of real-time transfer applies after release, so approval alone should not be read as proof that the money is already moving through Osko.
PayID’s role is therefore specific: it supports real-time transfers between bank accounts through Australia’s NPP, with Osko processing those payments. It does not erase the distinction between a withdrawal request and a completed transfer. Any description of an instant PayID payment should be read in that context, and not as a guarantee that the entire request-to-receipt process is immediate.
PayID Compared with Other Ways to Move Money
Payment methods differ in what they are designed to do as well as how quickly funds may arrive. PayID connects bank accounts through Australia’s New Payments Platform, while cards, e-wallets, bank transfers and cryptocurrency each follow their own process. A method that works for adding funds may not be available for a payout, so the deposit options shown on a payment page should not be taken as a promise that the same route can return money.
There is an important legal context for Australian readers. Under the Interactive Gambling Act 2001, providing real-money online casino games, including slots and table games, to people in Australia is illegal for operators. Offshore services may be inaccessible or blocked, and the presence of a payment logo does not change that legal position. The comparisons below describe payment mechanics and reported practices; they are not a recommendation to use an online casino service.
PayID and ordinary bank transfers
PayID is a bank-to-bank payment method associated with Australia’s New Payments Platform. Its key distinction from a conventional bank transfer is the payment rail: PayID payments can move in real time, whereas a traditional transfer may take longer to clear. That difference matters only once a payment has actually been released. A casino’s internal process and the banking transfer are separate stages, so a quick payment rail does not establish how long a service will take to approve or send a request.
A specialist review reports that traditional bank transfers may take as long as five business days to complete.
A specialist review reports that traditional bank transfers may take as long as five business days to complete. Treat that as a reported possibility, not a timetable that applies to every bank, transaction or service. Timing can differ according to the provider and the circumstances of the payment. In a comparison, the practical point is that conventional transfers may involve a longer wait after release than a real-time payment rail.
PayID also differs in how the recipient is identified: it uses a PayID identifier associated with a bank account rather than requiring you to rely only on conventional account details. That does not make it interchangeable with every payment option. Whether a PayID route is available, and whether funds can be returned through it, depends on the service’s payment arrangements. A service’s claim of an “instant withdrawal” should be read narrowly: instant can refer to the transfer phase after approval, not the full period from submitting a request to receiving funds.
Cards and e-wallets
Credit and debit cards are among the payment types reported as available on some real-money platforms, but a card deposit does not guarantee that a payout can be sent back to the same card. The exact sequence can also depend on the provider’s handling of the transaction. Before relying on a card as a route for money to return, check whether it is accepted for withdrawals rather than assuming that deposit support works both ways.
PayPal and Skrill are examples of e-wallets. An e-wallet keeps payment activity within a separate account or service rather than sending funds directly between bank accounts for every transaction. These are reported timings, not a guarantee for a particular transaction; processing arrangements differ and may change.
The comparison is therefore not simply “PayID is fast, wallets are slow” or the reverse. PayID’s distinguishing feature is its link to real-time bank payments once the sender releases funds. E-wallets have their own processing route and may be described as faster than conventional bank transfers, but a withdrawal still depends on the service sending it and the receiving wallet accepting it. For any method, distinguish the payment provider’s transfer time from the time spent waiting for a service to initiate payment.
Cryptocurrency
Some services also list cryptocurrency as a payment option. A specialist review describes cryptocurrency transactions as capable of being near-instant, but that is a generalised report rather than a dependable arrival time for a specific payment. Cryptocurrency does not use the same bank-to-bank path as PayID, cards or e-wallets, so comparisons based only on a label such as “instant” can be misleading.
The payment can involve more than the moment a transaction is initiated. The service must support the relevant cryptocurrency route, and the recipient must be able to receive funds through it. A crypto option is not automatically a substitute for a bank payout or a guarantee of quicker access to usable money. If you encounter such an option on an offshore platform, remember that its availability does not make the provision of real-money casino games to people in Australia lawful.
Legal Restriction
Under the Interactive Gambling Act 2001, providing real-money online casino games to people in Australia is illegal for operators.
Prepaid vouchers and deposit-only methods
Prepaid cards and vouchers, including Neosurf, are generally presented as ways to add funds rather than receive a cash-out. A specialist review reports that these products are commonly available for deposits but not withdrawals. The basic distinction is functional: a voucher can supply a prepaid value, but that does not necessarily provide a destination account to which a service can send winnings or a remaining balance.
Do not assume that a deposit route can be reversed. If a payment method is listed for deposits, look separately for confirmation that it is accepted for withdrawals. Where a voucher cannot receive a payout, another supported route may be required. That possibility can make a deposit method less suitable for someone who expects the same method to handle both directions, even before timing is considered.
How to compare the options
A useful comparison starts with the purpose of each method, then considers its reported speed:
| Method | Typical role in the payment options described | Timing context |
|---|---|---|
| PayID | Bank-linked payment through Australia’s real-time payment infrastructure | The transfer rail is real-time after release; this does not set the service’s approval time |
| Bank transfer | Moving money between bank accounts | A specialist review reports that completion may extend to five business days |
| PayPal or Skrill | E-wallet payments | E-wallet withdrawals are described as processed within 24 hours; a specialist review reports transactions taking hours rather than days |
| Credit or debit card | Card payments, with withdrawal availability depending on the service | Card payments may take several days |
| Cryptocurrency | Available at some services | A specialist review describes transactions as potentially near-instant, not as a guaranteed arrival time |
| Neosurf and similar vouchers | Generally used to deposit | A specialist review reports that withdrawals are generally not supported |
The table is a guide to reported use and timing, not a promise that every method will be offered or accepted. Payment menus can vary between services, and a method available for deposits may not be available for withdrawals. Australian-facing payment information should also be read in light of the law: operators are prohibited from providing real-money online casino services to people physically in Australia. A fast payment rail, a familiar wallet brand or a deposit voucher does not alter that restriction.
What Can Delay a PayID Withdrawal
PayID uses Australia’s New Payments Platform to move funds between bank accounts in real time, but that describes the payment rail—not how long it takes a casino to approve a payout. A request may remain pending while the operator checks the account or transaction. Only after approval and release can the transfer phase begin, so an “instant” label should not be read as a promise that money will arrive immediately after a request is made.
There is also an important legal context. Under the Interactive Gambling Act 2001, providing real-money online casino games to people physically in Australia is illegal. Casino-style games such as slots, poker and table games fall within the prohibited services. A payment method’s availability does not change that position, and a PayID transfer does not make an offshore casino service lawful.
Identity checks can hold up a first payout
A first withdrawal may bring an identity-verification request. Casinos must verify a player’s identity through KYC procedures before processing withdrawals, so a request can stay on hold until the required checks are completed. A specialist review of casino payout practices identifies first-time KYC as a common source of delay; it should be treated as a reported pattern, not a guarantee about every operator.
The practical issue is often not the payment method but whether the account information and verification documents can be matched. If the operator asks for documents, follow the instructions in its account notices and provide clear, current material through the stated channel. If something is unclear, ask what remains outstanding rather than repeatedly submitting different versions. Duplicate or inconsistent information can make it harder to resolve a check.
Completing identity verification early can significantly speed up later withdrawals. It does not remove the operator’s obligation to review a payout, and a previously verified account may still be checked again if a transaction or account detail needs clarification. But resolving routine identity questions before making a request can avoid having the first payout become the moment when basic account checks begin.
First requests may receive closer attention
A first payout can be a checkpoint for more than identity. The operator may need to confirm that the account belongs to the person requesting the funds, that the payment details match the account profile, and that the request meets its procedures. That is why the first withdrawal can take longer than later ones, even when PayID itself can transfer a released payment in real time.
A specialist review reports that first withdrawals can prompt identity requests and additional security checks. That is useful context, not a fixed timetable: operators differ, and an individual request may require further review for reasons that are not visible to the player. Avoid assuming that a pending status means a transfer has already been sent. It may still be waiting for the operator to complete its checks and approve release.
Larger requests may be reviewed manually
The amount requested can also affect the review path. A specialist review lists requests over $2,000 among possible causes of delay. This is not a universal threshold or a prediction that every request above it will be held; it is an example of how an operator’s review policy may treat a larger payout differently from a routine one.
Operators must disclose any manual review process for withdrawals exceeding $2,000. Read the relevant terms and withdrawal information rather than relying on a banner or a general claim about speed. A manual check can add an approval stage before the PayID payment is sent. Where an operator’s policy allows large withdrawals to be released in instalments, the total amount may also arrive in separate payments rather than as one transfer.
Operators must disclose any manual review process for withdrawals exceeding $2,000.
Some specialist reviews describe automatic approval for withdrawals below $5,000 at certain top-tier PayID casinos. That is a report about selected services, not a market-wide rule or a reliable promise. “Auto-approval” does not establish that every request qualifies, nor does it remove required identity checks, account conditions or other review steps. The relevant operator’s current terms are the only useful guide to its process—and they do not alter the legal status of online casino services in Australia.
Review windows and unanswered requests
An operator’s internal review window can be longer than the transfer itself. A request submitted outside the hours when staff process withdrawals may wait until the next review period. A specialist review also notes that some services advertising instant payouts have taken up to 24 hours because of internal review. This is a reported example, not a standard processing time; it shows why a speed claim needs to be separated from the approval stage.
If a request remains pending, check the account’s transaction history and any messages requesting information. Note whether the displayed status says it is under review, approved, or sent; those labels describe different stages. If the status does not explain what is happening, contact the operator through its stated support channel and ask whether a document, account check, or manual approval is outstanding. Avoid sending sensitive details through an unverified contact route.
A delay is not necessarily evidence that a PayID transfer has failed. The operator may not yet have released the funds, or the request may be waiting for checks. Conversely, a payment described as approved is not the same as a confirmed receipt. Keep the confirmation and transaction reference if one is provided, and raise a query with the operator if the status and account activity do not match.
Bank processing can matter after release
A specialist review identifies bank processing windows as another possible source of delay. PayID is designed for real-time transfers through the NPP, but the time a casino takes to approve a payout and the time a receiving bank reflects a payment are separate parts of the process. A request can therefore be held before release, or the account may not show the funds as expected after release.
When seeking an update, ask which stage the payment has reached rather than relying only on the word “instant.” If it is still awaiting approval, the bank cannot complete a transfer that has not been sent. If the operator confirms release, the transaction reference and the receiving account details can help clarify the next step. Do not assume a delay is resolved merely because a payment method is described as real-time.
The most useful way to interpret a PayID payout estimate is as a sequence: the operator checks and approves the request, releases it, and the payment rail then carries the funds. Identity verification, first-request scrutiny, a larger amount, a manual review window, or bank processing may affect one of those stages. None of those stages makes real-money online casino services lawful for people in Australia; payment technology and the legal status of the service are separate matters.
Bonuses, Limits and Details to Check Before Cashing Out
A cash-out can be blocked by conditions that have nothing to do with the payment rail. Bonus rules, account details, withdrawal caps and fees can all affect whether a request is eligible and how much reaches an account. These are terms to understand before putting money at risk, not assurances that a real-money casino is lawful or available to people in Australia.
That distinction matters here. Under Australia’s Interactive Gambling Act 2001, operators must not provide real-money online casino games to people physically located in Australia. A bonus advertised as a no-deposit offer does not change the legal status of the service or make its terms safer. Avoid treating a promise of an instant PayID cash-out as evidence that an operator can lawfully serve Australian players.
Read the bonus terms before accepting an offer
A bonus may come with a wagering requirement: a condition that must be completed before funds associated with the offer can be withdrawn. The terms can define what counts towards that requirement and whether it applies to bonus funds alone or to the combined deposit and bonus. Bonus-funds-only wagering is the preferable structure because it does not attach the same requirement to the deposited amount. Even so, you need to understand the actual conditions before accepting anything.
Do not assume that a balance displayed in an account is immediately withdrawable. Bonus-related funds may remain subject to their conditions, and attempting to cash out before those conditions are met can make the request ineligible. Players must complete applicable wagering requirements before attempting a withdrawal. If the terms are unclear about which balance is restricted, what activity counts, or when the restriction ends, the uncertainty itself is a reason not to proceed.
A no-deposit bonus deserves the same scrutiny. The label alone does not tell you whether a balance can be withdrawn, what conditions attach to it, or whether a payment method is required to receive any funds. Do not infer the answer from promotional wording. Only the terms state the conditions, and those terms do not override Australian law.
Read the withdrawal and bonus rules together rather than treating them as separate pages. A bonus may affect eligibility, while a separate cash-out rule may set the minimum or maximum amount that can be requested. If the conditions appear inconsistent, do not rely on the more favourable interpretation without written clarification.
Match the PayID details to your account
Where PayID is involved, the details should match those used for the deposit, and the destination account must be linked to the casino profile. Operators generally require funds to be returned to the original payment method where possible. Using different PayID details can create a security concern and may prompt a review, even if you control both accounts.
- Check the PayID identifier in your profile against the one used for deposit
- Use the official account process to update payment information
- Enter another person’s PayID to resolve a mismatch
- Share sensitive account details through public messages
Before submitting any request, check the PayID identifier saved in the profile against the one used for the deposit. Look for typing errors and make sure the destination belongs to you. A name or account mismatch is not a harmless way to redirect funds: casinos must verify identity before processing withdrawals, and a payout should go only to an account linked to the player’s profile.
If the payment details have changed, do not try to work around the mismatch by entering another person’s PayID. Use the account’s stated process for correcting or updating payment information, and provide only information requested through the appropriate account channel. Keep a record of what you submitted and any response, without sharing sensitive account details in public messages.
Check each type of withdrawal limit
A withdrawal limit can be set per transaction, but that may not be the only cap. Weekly or monthly cash-out limits may apply separately, so a request that fits within a single-transaction maximum could still exceed the amount allowed over the relevant period. A casino’s policy can also restrict the amount available to withdraw.
A specialist review may describe reputable PayID casinos as publishing minimum and maximum withdrawal limits clearly. Treat that as a useful standard to look for, not proof that any particular service is lawful or that its terms will suit you. The relevant terms should make clear the minimum request, the maximum per transaction and any broader cash-out cap. If the wording leaves you unable to tell how much you can request, do not assume that the displayed balance can all be withdrawn at once.
Large withdrawals may be released in instalments under an operator’s policy. That can affect how much is paid in each transfer and how the overall amount is handled. Check whether the policy describes instalments and whether a separate overall cap applies. Do not rely on a headline limit alone if the detailed terms set additional conditions.
Look for fees before confirming
A fee can reduce the amount received even when a request is otherwise eligible. Filmink.com.au has reported that a transaction fee may apply to PayID withdrawals. That is not a statement that every PayID transaction carries a fee; it is a reason to check the terms for the specific service and request.
Look for any fee disclosure before confirming a cash-out, and distinguish a fixed charge from a deduction expressed in another way. If a fee is mentioned without explaining when it applies or how it is calculated, ask for clarification before proceeding. Do not treat an estimate shown in a promotional message as a substitute for the terms governing the transaction.
The terms should also explain withdrawal limits, fees and processing conditions clearly. Save a copy of the relevant wording at the time you review it, since pages and policies can change. A record helps you compare what was disclosed with any later account message without relying on memory.
A practical pre-request check
Before submitting a withdrawal request, confirm that any bonus conditions have been met; that the PayID details match the deposit and are linked to your profile; and that the requested amount falls within both the per-transaction and any weekly or monthly limits. Check for fees and any instalment policy, too. If any part of the terms is unclear, pause rather than making a request on an assumption.
These checks can help identify account or transaction conditions, but they cannot make a prohibited service lawful. An instant-payment label does not guarantee that a request is eligible, that the full balance can be withdrawn, or that the destination details will be accepted. In Australia, the legal restriction on operators providing real-money online casino games remains central, regardless of the bonus language or payment method advertised.
How fast are withdrawals?
PayID transfers can arrive in real time once the operator releases them, but approval and review happen first and can delay the full withdrawal. First-time identity checks, larger withdrawals and bank processing windows may add time.
What are easy withdrawal casinos?
Reviews cited Fastpay Casino at an average of 47 seconds, PlayAmo at 68 seconds and National Casino at 3.2 minutes. These are reported payout times, not guarantees; checks can delay a withdrawal.
How do you choose the best easy withdrawal casino site?
Check that withdrawal limits and fees are clearly published, whether PayID withdrawals can be auto-approved, and what identity checks apply. Completing verification early and checking weekly or monthly cashout limits can help you avoid delays.
What payment methods are available?
Options may include PayID and other bank transfers, credit or debit cards, PayPal, Skrill and, at some sites, cryptocurrency. Prepaid vouchers such as Neosurf are generally for deposits rather than withdrawals.
Can I legally deposit and withdraw money to online casinos?
Operators are prohibited under the Interactive Gambling Act 2001 from providing real-money online casino games, including slots, poker and table games, to people in Australia.
Prepared by the Lucky Block Casino editorial staff.