Online casino payment methods in Australia: key details
 Available in AU
Payment routes can differ between deposits and withdrawals, and an option shown by an offshore site does not make its service lawful in Australia.
Table of Contents
- The Payment Options You May Encounter
- Deposits and Withdrawals May Follow Different Routes
- Australian Bank Transfers: PayID and BPAY
- Payment Gateways, Cards and Blocked Transactions
- Vouchers and the Limits of SMS-Style Payment Systems
- Check the Payment Portal Before You Commit
- Provider Fees and the Time It Takes to Cash Out
- Instant Payments: Check What ‘Instant’ Actually Means
- Payment Apps and Digital Wallets on Your Phone
- Using Payment Methods on a Mobile Device
The Payment Options You May Encounter
Payment labels can make an online checkout look more straightforward than it is. For someone in Australia, the first distinction is not which option sounds familiar, but whether the service is lawful and available for the activity in question. The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games, including pokies, to people physically located in Australia. A payment option appearing on an offshore site does not change that position or make the service compliant with Australian law.
In general descriptions of online payments, the main categories include bank-based transfers, digital wallets, prepaid vouchers, cards and cryptocurrency. They are not interchangeable: each relies on a different provider and may come with different conditions. An operator’s displayed options can also vary, so a list on one site should not be treated as a standard menu for every site. This is a broad way to understand the terminology, not a recommendation to use an offshore casino.
Bank-based options connect a payment to a financial account. In Australia, PayID links a mobile number, email address or ABN to a bank account through the New Payments Platform, and every major Australian bank supports PayID. That describes the payment network, not whether a casino operator offers PayID or whether a real-money casino service is lawful. BPAY is another name you may see in discussions of bank payments, but its role and timing are distinct from PayID; the details belong to the provider and service being described.
Digital wallets and e-wallets are accounts or services used to handle payments electronically. Names such as Skrill, Neteller and MuchBetter may appear in payment information, but recognition of a brand does not establish that it is available for a particular transaction. The same caution applies to familiar phone-based wallets. A payment made from a phone is not automatically a separate “phone payment” category: the underlying method may still be a bank account or a digital wallet.
Prepaid vouchers are a different kind of option. The value available is limited to what has been loaded onto the voucher, so the spending boundary is visible in advance. That does not make a voucher a complete payment solution; the conditions attached to a service still matter. Vouchers are one of several payment terms a reader might encounter, rather than a signal that an online casino is appropriate or lawful to use.
Cards are also widely recognised as a payment category, but familiarity should not be confused with acceptance. Australian financial institutions block many standard Visa and Mastercard transactions to offshore casinos. A card logo on a page is therefore not proof that a transaction will go through, and online gambling services must not accept credit card payments. Treat claims about card access with particular care.
Cryptocurrency names, including Bitcoin and Ethereum, can appear in online casino payment discussions. Their presence in a payment list is not an endorsement or a suggestion to transfer funds. Australian constraints prohibit accepting digital currency for online wagering, and blockchain transfers are irreversible and have no chargeback option. If a transfer is sent to the wrong address or an intended service cannot be accessed, the usual card-style reversal is not available.
A specialist review has reported that payment methods can differ between deposits and withdrawals. Treat that as a reason to read descriptions carefully, not as a rule that applies to every operator. More broadly, the phrase “Australian casino payment options” can describe methods mentioned in the market; it does not establish that real-money online casinos may lawfully serve Australians. No payment solution removes that distinction. A payment page is not evidence of legal status, consumer protection or dependable access.
Deposits and Withdrawals May Follow Different Routes
A payment option shown for adding money does not, by itself, tell you how funds could be returned. Operators can set different conditions for deposits and withdrawals, so treating a listed casino payment method as a complete, two-way route can leave you with an unexpected problem later.
A specialist review describes PayID availability as dependent on the operator and says withdrawal support needs to be checked separately. That is a useful distinction, not a guarantee about what any particular service currently offers. Payment arrangements can change, and the deposit screen may show only the ways to send money in. Before you enter payment details, look for clear information about withdrawals and whether the method you are considering is eligible for them.
Attention: A successful deposit only confirms that funds were sent; it does not guarantee that the same method can be used for withdrawals or that payouts will follow expected terms.
This matters because a successful deposit confirms only that money went in. It does not establish that the same method can receive a payout, that another route will be available to you, or that you will be able to access funds on the terms you expect. If the return route is unclear, the sensible response is not to assume it will be sorted out later. Do not send money until you understand what the stated withdrawal options are and what conditions apply.
The mismatch can also affect your planning. You might be prepared to use one payment service to add funds but unwilling or unable to use the method offered for returning them. A site may describe several casino payments without making clear which are for deposits, which are for withdrawals, and which can serve both purposes. Read the labels and terms carefully; a general list of online casino payment methods is not the same as a confirmed cash-out route.
PayID illustrates why the two sides need separate attention. A payment page might present it as an option for deposits, but that does not answer whether withdrawals through PayID are supported. Confirm the withdrawal position independently rather than inferring it from the deposit menu. If the information is missing, contradictory or difficult to understand, treat that uncertainty as a reason to pause—not as a minor detail to resolve after you have paid.
There is also a broader issue that a payment method cannot settle: whether the service itself may lawfully provide online casino games to people in Australia. Under the Interactive Gambling Act 2001, providing real-money online casino games to people physically located in Australia is illegal for operators. A familiar payment brand, a working deposit page or a stated withdrawal policy does not change that legal position. This is not a recommendation to use an offshore service.
If you are assessing a payment arrangement, keep the questions distinct: is the service permitted to offer the activity, what does its payment information say about deposits, and what does it say about withdrawals? A clear answer to one does not supply an answer to the others. In particular, do not regard a deposit option as evidence that a withdrawal route has been arranged for you.
No-deposit promotions can also carry wagering, identity-check and withdrawal conditions. The word “no-deposit” does not necessarily mean that winnings are immediately withdrawable or free of conditions. Read the terms before taking any action, and do not rely on a promotion’s headline as a description of what you can cash out.
A careful decision begins before money moves. If the available information does not identify a withdrawal route and its conditions, you cannot sensibly assess the full payment risk. For Australian readers, that uncertainty sits alongside the legal restriction on operators providing real-money online casino games in the country; it should not be mistaken for a routine inconvenience or an invitation to try another payment method.
- Verify the available withdrawal routes before depositing
- Read the specific terms of no-deposit promotions
- Confirm the conditions for accessing your funds
- Assume a deposit method is also a cash-out route
- Rely on a promotion’s headline for withdrawal rules
- Send money until the return route is clear
Australian Bank Transfers: PayID and BPAY
PayID and BPAY are both linked to bank payments, but they work differently and should not be treated as interchangeable. PayID connects a chosen identifier—such as your mobile number, email address or ABN—to an Australian bank account through the New Payments Platform. BPAY is a separate bill-payment service. Whether either appears as an option depends on the payment arrangements of the service you are viewing; neither is guaranteed to be available everywhere.
PayID is supported by every major Australian bank. That broad bank support does not mean every casino payment portal offers it, or that a payment will be accepted simply because your bank supports PayID. A specialist review describes PayID as the primary Australian-dollar deposit method at most offshore operators. Treat that as a report about the operators covered by that review, not as a promise about any particular site or a permanent market-wide rule.
If PayID is presented, check the payment instructions carefully before authorising a transfer. Confirm that the identifier and recipient details match what the portal displays, and do not rely on a saved detail from an earlier transaction. A familiar payment label does not tell you who will receive the funds, what the operator will do with them, or whether the underlying service is lawful.
That legal distinction matters in Australia. The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games, including pokies, to people physically located here. A payment method’s availability does not make an offshore casino lawful or compliant with Australian rules. Nor should you treat the presence of PayID or a bank transfer option as evidence of regulatory approval.
BPAY has a different practical profile. A specialist review gives its processing time as one to two business days, so it is not the choice to rely on when you expect funds to arrive for immediate play. The same type of review characterises BPAY as rarely used for real-time gameplay and as a possible backup when PayID is unavailable. Those descriptions reflect reported use, not a guarantee that a particular merchant will accept BPAY or process it on the same schedule.
The distinction is worth keeping clear: PayID’s connection to participating Australian bank accounts does not establish how quickly a specific casino portal will handle a deposit. BPAY has a stated processing window, but that does not make it available at every operator. Check the payment page itself rather than assuming that a method offered by your bank is also offered by the service.
Before sending money, read the displayed instructions and terms, and pause if the recipient details or payment purpose are unclear. Do not treat a successful bank transaction as proof that a casino is authorised to serve Australian customers. If you have already transferred funds and something does not match the stated process, contact your bank promptly and keep the transaction record. A bank-transfer label can describe how money moves; it cannot settle whether the service receiving it is lawful.
Payment Gateways, Cards and Blocked Transactions
A payment gateway is the technology that carries a payment request from an online checkout to the relevant payment processor. It helps pass transaction details along and return a result, such as approval or rejection. It does not decide whether a particular payment method is available to you, and it cannot override a bank’s decision to block a transaction.
A payment gateway is the technology that transmits a payment request from the checkout to the processor; it cannot override a bank’s decision to block a transaction.
That distinction matters when you see Visa or Mastercard listed. A specialist review reports that deposits made with these cards can be processed instantly when accepted. But speed describes the time taken for a successful transaction; it says nothing about whether your financial institution will allow it in the first place.
A specialist review also reports that Australian financial institutions block many standard Visa and Mastercard transactions directed to offshore casinos. So a card logo on a payment page is not assurance that a payment will go through. The gateway may pass the request on, but the issuing institution can still decline it. Repeated attempts are unlikely to resolve a block imposed by the institution, and you should not treat card payments as a dependable route for online gambling.
The restriction is also important when thinking about card types. Credit cards and credit-related products should not be used to fund online wagering. A payment page presenting a card option does not make credit funding appropriate or ensure that the transaction is permitted by the institution. If you are unsure what a listed option means, do not enter your details until you have established how it is funded and whether the payment can be accepted.
A gateway can make a checkout feel seamless, but the interface is only one part of the transaction. The operator’s configuration, the payment processor and your financial institution can all affect the outcome. A decline may therefore occur even when the page appears to offer cards and the gateway itself is functioning.
If a card payment is rejected, check your bank’s explanation rather than assuming the problem is a temporary technical fault. Avoid trying different card details or repeatedly resubmitting the same payment. Those steps do not change an institution’s decision and may leave you uncertain about whether a pending request has been resolved.
Before proceeding, consider whether the payment method is allowed and whether your bank will process it. Do not rely on a fast-processing claim as evidence that a transaction will be accepted. In Australia, many standard card transactions to offshore casino services are blocked, so a listed Visa or Mastercard option should not be treated as a reliable way to pay.
Vouchers and the Limits of SMS-Style Payment Systems
A prepaid voucher can put a firm boundary around what you spend: once its loaded value is used, it cannot fund further payments. That makes paying via a voucher different from using a payment method linked to an account with additional funds. The cap is practical, but it does not make a transaction risk-free or change the rules that apply to online gambling.
There is an important limit on the other side of the transaction. A voucher used to add funds generally cannot receive a withdrawal. If money is paid into an account through a voucher, you may need a separate cashout method, and the operator’s terms determine what route is available. Check that route before making any payment; do not assume the original voucher can be used to get money back.
Legal Restriction
Under the Interactive Gambling Act 2001, it is illegal for operators to provide real-money online casino games to people physically located in Australia.
This matters when comparing an online casino payment system with a prepaid option. A payment method may appear simple at the point of purchase, while leaving you without a matching way to receive funds. The voucher’s loaded value sets a spending ceiling, but it does not settle how any later withdrawal would be handled. Treat those as separate questions.
Do not infer that a named voucher is accepted just because it is sold locally or appears in a general discussion of casino payment systems. Availability can depend on the specific service, and an operator’s payment page may not show the same choices as another site. The same caution applies to references to CashtoCode or eCheck: a search result or mention elsewhere is not confirmation that either is available to you.
SMS-style payment is another area where assumptions can cause trouble. A phone-based payment description does not establish that a casino accepts charges through a mobile carrier, or that such a charge could be used for a withdrawal. Do not treat casino SMS payment as an available route unless the operator’s own payment information explicitly confirms it. Even then, read the terms rather than relying on a label.
The broader legal context also matters. Under the Interactive Gambling Act 2001, operators may not provide real-money online casino games to people physically located in Australia. A payment feature does not make such a service lawful or endorsed for Australian use. Be cautious about treating any payment page as an assurance of legality or protection.
Before paying, look for clear information about whether a voucher is accepted, what happens to unused value, and how withdrawals are handled. If the cashout route is unclear, pause rather than adding funds. A capped payment can help you limit the amount you put into a transaction, but it cannot resolve unclear terms or create a withdrawal option that is not offered.
Check the Payment Portal Before You Commit
A payment portal can show what an operator says it accepts, but it cannot establish that the service is lawful for people in Australia. The Interactive Gambling Act 2001 makes it illegal for operators to provide real-money online casino games to people physically located here. Treat a portal’s payment information as something to assess, not as an endorsement or a reason to proceed.
If you are reviewing a portal, read the deposit and withdrawal information separately. A specialist review reports that PayID deposit availability depends on the operator and that withdrawal support needs its own check. Do not assume that a method shown beside a deposit option will also be offered for withdrawals. Look for clear wording about which routes are supported for each transaction, and be wary of vague labels that do not explain the distinction.
Check the currency before relying on any displayed balance or payment amount. If the account converts Australian dollars to euros, the conversion may cost 2–4%. That cost can affect the value you receive, even when the portal displays a familiar payment method. Confirm which currency will be used and whether the conversion charge is explained before any payment is attempted.
Also read the operator’s terms for account and verification requirements. A specialist review describes possible checks that include a government-issued identity document, a recent proof of address dated within three months, and evidence that the payment method belongs to you or is authorised for your use. If those requirements are unclear, do not assume they will be waived later. A request for documents can affect access to an account or its funds, so understand what may be asked for before sharing personal information.
Look beyond the payment panel to charges and account terms. A specialist review reports that some casinos apply a $10 monthly inactivity charge after an account has had no login for 90 days. Those terms are not universal, so check the specific operator’s wording rather than treating the figure as a general rule. Find out what counts as inactivity, when a charge begins, and whether the terms describe any exceptions.
Names such as POLi, Neosurf and PayPal should not be treated as proof that a particular service is accepted or suitable. A portal’s list may be incomplete, change over time, or describe deposits without explaining cashouts. PayPal has prohibited gambling transactions in Australia since 2021, so its familiar name should not be read as a dependable casino payment route. The same caution applies to any method you recognise: the name alone tells you neither whether it is available nor what conditions apply.
Before taking any step, make sure the portal’s terms are specific about currencies, possible checks, charges and withdrawal routes. If those details are missing or inconsistent, do not rely on assumptions to fill the gaps.
Provider Fees and the Time It Takes to Cash Out
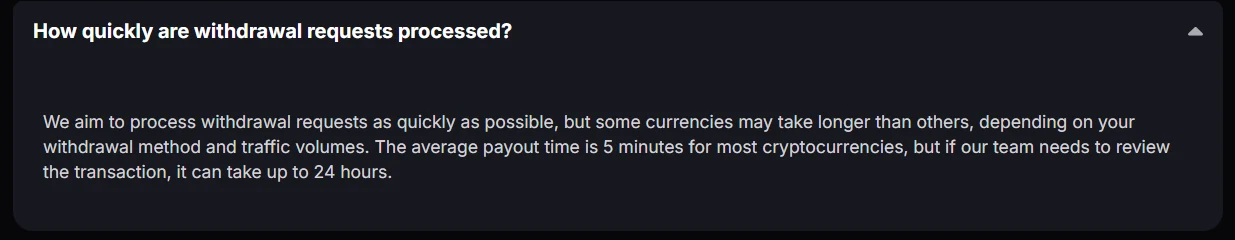
A withdrawal’s cost and arrival time can depend on both the payment service and the casino’s own handling of the request. Treat published figures as terms to verify for the specific account and transaction, not as a standard that applies across providers. A payment provider may move funds quickly after a request is released, while the casino’s review or processing queue adds time beforehand.
Bank transfers can involve a wait at either stage. A specialist review describes casino withdrawals as sometimes being handled manually once or twice a week; in the example it gives, a request made on Friday could reach the player by Wednesday. The same review says a traditional bank-transfer cashout may take as long as five days. Those timings are reported characteristics, not a promise about an individual withdrawal. Check whether the casino’s stated timeframe includes its own approval period as well as the transfer to your bank.
E-wallet withdrawals may take a different route. A specialist review reports that a MuchBetter withdrawal can be faster than a traditional bank transfer, but that comparison does not establish how long a particular casino will take to approve or release funds. For Skrill, a specialist review gives one to two days for a withdrawal to a bank. It also reports that some casinos apply a transaction fee of one to three per cent. The word “some” matters: fees and processing terms can vary, so confirm the amount and whether it is charged by the casino or the provider before relying on that estimate.
Can be handled manually once or twice a week, with traditional cashouts potentially taking up to five days.
Reported to be faster than traditional bank transfers for withdrawals.
Withdrawals to a bank may take one to two days, with some casinos applying a 1–3% transaction fee.
When comparing casino payment providers, look at the full cost of getting money into your bank account, not just the name of the withdrawal method. A fee may reduce the amount received, and a shorter provider transfer time does not remove delays that occur before the casino releases the withdrawal. Check whether the displayed fee is a percentage or a fixed charge, which currency the transfer will use, and whether any conversion cost is stated. Do not assume that a fee quoted for one service applies to another.
Keep a record of the withdrawal amount, the fee shown before confirmation, and the time the request was submitted. If the payment has not arrived within the timeframe the operator gave you, that record can help you ask a focused question about whether the request is still being reviewed or has already been sent to the provider. Terms can change, so recheck them in the payment area before making a decision.
Instant Payments: Check What ‘Instant’ Actually Means
“Instant” can describe one part of a payment, not the whole process. A transaction may be authorised or sent quickly, while the casino’s payment integration determines whether the account is credited at once. A method’s speed also tells you nothing about whether a particular operator offers it. Those are separate questions, and a label on a payment page does not settle both.
PayID is linked to an Australian bank account through the New Payments Platform, but that does not establish that a casino supports it or that a deposit will be credited instantly. Availability depends on the operator. Treat any claim about speed as specific to the payment route and service being described, rather than as a guarantee for every transaction.
BPAY illustrates the difference. A specialist review gives a processing window of one to two business days for BPAY payments. The same review describes BPAY as rarely used for real-time gameplay and as a possible fallback when PayID is unavailable. That is a slower route by design, not an instant option; its presence in a cashier does not mean funds will be ready for immediate use.
Before relying on an “instant payment” description, look for the operator’s own explanation of what happens after you submit a transaction. Check whether it refers to payment authorisation, the transfer itself, or funds appearing in an account. Also confirm that the method is actually listed for the relevant transaction. A payment brand being familiar, or appearing in a general list of methods, is not proof of casino integration.
This distinction matters especially when timing affects a decision. Do not assume that a fast bank or wallet service makes every casino transaction immediate, and do not infer availability from the word “instant.” If the payment page does not explain the timing clearly, pause rather than treating an estimate as a promise.
Australia’s Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people located in the country. Payment-speed claims do not change that legal position. If you are assessing information about payment services, keep availability, processing speed and the law in Australia separate; one does not establish either of the others.
Payment Speed
“Instant” typically describes only one part of the process and does not guarantee immediate account credit or legal availability in Australia.
Payment Apps and Digital Wallets on Your Phone
A payment app can feel familiar without being available for every kind of transaction. PayID, for instance, may appear as a deposit option at one operator and be absent at another. A specialist review describes its availability as operator-dependent, so check the payment information for the specific service rather than assuming that a method supported elsewhere will work there. The same review advises checking withdrawal arrangements separately: a deposit option does not establish that withdrawals can be made through it.
PayID is connected to Australian bank accounts through the New Payments Platform, using details such as a mobile number, email address or ABN. That connection explains how the service works with participating bank accounts; it does not mean an online casino accepts PayID. Availability has to be confirmed at the operator, and you should not treat a deposit facility as evidence of a withdrawal route.
Apple Pay also has a familiar phone-based process. A specialist review describes deposits being authorised through the digital wallet on a phone, with biometric authentication used to confirm the payment. That can make the transaction feel straightforward, but convenience is not the same as acceptance. A casino’s payment page must specifically show Apple Pay for the method to be available. Do not assume it can be used to cash out: Apple Pay should not be treated as a withdrawal method.
PayPal is different. It has prohibited gambling transactions in Australia since 2021, so a PayPal account should not be considered an option for funding online casino gambling here. A logo or a general reference to digital wallets is not enough to establish that a particular payment is supported; check the named methods and their permitted uses.
There is also a more important boundary than app compatibility. Under the Interactive Gambling Act 2001, operators cannot provide real-money online casino games, including pokies, to people physically located in Australia. A payment feature does not make such a service lawful or locally authorised. Be cautious about treating an app’s presence on your phone, or a payment page that accepts details, as a sign that the underlying gambling service is permitted.
Using Payment Methods on a Mobile Device
When choosing an online casino payment method in Australia, check the deposit and withdrawal details that matter to you, as well as the operator’s licensing information. These notes highlight the payment-related facts available for each option.
License: Curacao The available detail for Golden Pokies is its Curaçao licence; no specific payment methods, limits or payout times are provided here.
License: Curacao Gaming Control Board OGL/2023/176/0095 (Hollycorn N.V.) GoldenCrown is listed with a Curaçao Gaming Control Board licence, OGL/2023/176/0095, held by Hollycorn N.V. No payment-specific details are provided.
License: Curacao · Min. deposit: A$20 (POLi) Lucky Dreams lists a A$20 minimum deposit using POLi, giving you a stated entry point for that payment method. It is also listed as Curaçao-licensed.
License: Curacao eGaming OGL/2023/174/0082 (Dama N.V.) · Min. deposit: A$15 LevelUp Casino lists a A$15 minimum deposit and a Curaçao eGaming licence, OGL/2023/174/0082, held by Dama N.V. The deposit method is not specified.
License: international iGaming licence – jurisdiction not named in the source · Payout speed: PayID 1-24 hours · Min. deposit: A$30 (PayID from A$10) House of Pokies lists PayID payouts in 1–24 hours and a A$30 minimum deposit, with PayID deposits from A$10. Its source describes an international iGaming licence but does not name the jurisdiction.
License: Curacao eGaming (Roby Games Ltd) Roby Casino is listed as licensed by Curaçao eGaming under Roby Games Ltd. No payment methods, deposit limits or payout times are specified.
License: Curacao (operating since 2017) · Min. deposit: A$20 Uptown Pokies is listed as operating since 2017 and as Curaçao-licensed, with a A$20 minimum deposit. No deposit method is specified.
License: Curacao, operated by Dama N.V. 7Bit Casino is listed as Curaçao-licensed and operated by Dama N.V. No payment-specific details are provided.
License: Curacao · Payout speed: crypto 30-60 minutes, fiat 1-5 days · Min. deposit: A$10 Wild Tokyo lists crypto payouts in 30–60 minutes and fiat payouts in 1–5 days, with a A$10 minimum deposit. It is also listed as Curaçao-licensed.
License: Tobique Gaming Commission · Payout speed: crypto ~10-15 minutes, fiat 1-5 days · Min. deposit: A$30 SkyCrown lists crypto payouts in approximately 10–15 minutes and fiat payouts in 1–5 days, with a A$30 minimum deposit. Its stated regulator is the Tobique Gaming Commission.
A phone can make a payment feel straightforward, but the small screen does not make the transaction safer or change whether the service is lawful. In Australia, providing real-money online casino games to people in the country is prohibited under the Interactive Gambling Act 2001. Treat any mobile payment prompt connected to such a service with care; a familiar checkout experience is not evidence that the underlying activity is permitted.
A specialist review describes Apple Pay deposits as being made through a phone’s digital wallet, with biometric authentication used to approve the payment. That can mean confirming the action on the device rather than entering card details into a page. It does not mean Apple Pay is accepted by a particular site, that a payment will go through, or that the method can be used to receive money. Do not assume a mobile wallet offers a route for withdrawals.
Before confirming any online payment, pause to check what the screen is asking you to approve. Make sure the amount and recipient match your intention, and do not proceed if the details are unclear or the page asks you to share a passcode or other security information outside the normal device prompt. A request to authenticate is an approval step, not a guarantee that the transaction can be reversed.
Mobile pages can also make terms and payment conditions harder to review. If you cannot read the relevant information comfortably, close the prompt and use a larger screen rather than approving first and checking later. Avoid saving payment details on a device you share with someone else, and keep your phone’s security settings under your control.
The same caution applies when a service mentions a named wallet or a mobile payment option. Availability on a phone is not proof of legal status, and the appearance of a payment logo does not confirm how funds would be handled. Do not send money to an offshore casino service from Australia.
Are there fees for using e-wallets at Australian online casinos?
Yes, fees may apply: some casinos charge 1–3% for Skrill transactions, and Neteller charges 1.45% when you fund it by credit card. Check the specific payment and withdrawal terms before using an e-wallet.
Do Australian online casinos charge fees for deposits or withdrawals?
They may: bank transfers can incur a flat $5–$15 fee, and some casinos charge 1–3% on Skrill transactions. Crypto withdrawals are usually free, but currency conversion can cost 2–4%.
What is PayID and how does it work in Australian online casinos?
PayID links your mobile number, email address or ABN to your Australian bank account through the New Payments Platform. Whether an operator offers it for deposits depends on that operator, and you should check separately whether it supports PayID withdrawals.
What happens if my bank blocks a transaction to an online casino?
The payment may not go through: Australian financial institutions block many standard Visa and Mastercard transactions to offshore casinos. A card logo on a site does not guarantee that your bank will process the payment.
Are credit cards allowed for online casino payments in Australia?
No. Online gambling services must not accept credit card payments, and Australian financial institutions block many standard card transactions to offshore casinos.
Prepared by the Lucky Block Casino editorial staff.